
Table of Contents
- The Short Answer: No, Standard Policies Exclude Flood Damage
- Difference Between Water Damage and Flood Damage
- What Your Homeowners Policy Actually Covers
- Understanding the Flood Insurance Waiting Period
- How to Buy Flood Insurance: NFIP and Private Options
- Flood Zones, Elevation Certificates, and Your Premium
- The Claims Process: What to Expect After Flooding
- Conclusion: Protecting Your Home From Rising Water
- Frequently Asked Questions
Last Updated: September 5, 2026
The Short Answer: No, Standard Policies Exclude Flood Damage
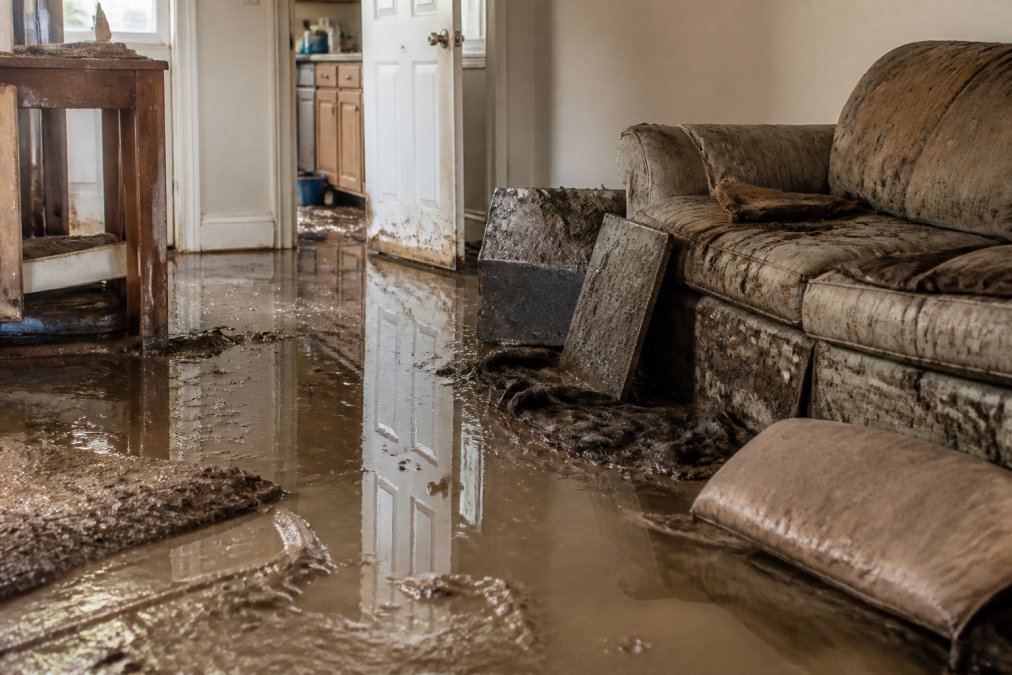
The direct answer is no. A typical homeowners policy in Texas explicitly excludes flood damage, defined as rising water or surface water entering your home from outside (tdi.texas.gov). Flood risk is concentrated in specific geographic areas, making it uninsurable through standard risk pools.
Flood damage is a distinct peril requiring separate coverage. At Glenn Davis Insurance, we regularly speak with homeowners who assume their policy protects them after heavy rain, only to discover the exclusion during a claim.
Difference Between Water Damage and Flood Damage
Water damage refers to sudden and accidental water intrusion from inside your home, such as a burst pipe, an overflowing appliance, or a leaking roof. Flood damage refers to water that rises from outside, including storm surge, overflowing rivers, or heavy rainfall that saturates the ground and enters at ground level.
This distinction matters because it determines which policy responds. Damage from a broken washing machine hose is typically covered under your homeowners policy. Damage from a creek overflowing its banks is not. The National Flood Insurance Program definition of flooding clarifies that flooding involves water on the surface of normally dry land, which is why standard carriers exclude it.
A common mistake is assuming groundwater seepage through your foundation counts as a covered water claim. Most insurers treat this as flood-related and deny it under a standard policy. Sump pump failure often falls into a gray area, so ask your agent whether your policy includes a sump pump endorsement.
What Your Homeowners Policy Actually Covers
Your standard homeowners policy covers sudden and accidental damage from perils like fire, wind, hail, lightning, and theft, plus water damage from internal sources like burst pipes and appliance failures, provided the damage was sudden.
What it does not cover is rising water, surface water, or groundwater entering from outside, regardless of whether it came from a hurricane, flash flood, or backed-up drainage system. Gradual damage from long-term leaks is also excluded as a maintenance issue.
| Type of Water Event | Covered by Standard Policy? | Why |
|---|---|---|
| Burst pipe | Yes | Sudden and accidental, internal source |
| Appliance overflow | Yes | Sudden and accidental, internal source |
| Roof leak from wind-driven rain | Yes | Wind is a covered peril |
| River or creek flooding | No | Rising water, external source |
| Storm surge | No | Rising water, external source |
| Groundwater seepage | No | Typically classified as flood |
| Sewer backup | Often No | Requires separate endorsement |
Sewer backup coverage is usually sold as an endorsement or rider. Without it, damage from a backed-up municipal line is typically not covered, even though it originates from inside your plumbing system.
Understanding the Flood Insurance Waiting Period
Flood insurance does not take effect immediately. The NFIP imposes a standard 30-day waiting period before a new policy becomes active (fema.gov).
This waiting period prevents homeowners from buying coverage only after a storm is forecast. Flood insurance must be purchased well before the threat arrives.
The 30-day waiting period is the single most important reason to buy flood insurance early. If you wait until rain is forecast, you will be unprotected during the exact event you were worried about.
Private flood insurers sometimes offer shorter waiting periods, but these policies vary. Factor the waiting period into your timeline.
How to Buy Flood Insurance: NFIP and Private Options
There are two primary ways to purchase flood insurance: through the National Flood Insurance Program or through a private insurer.
The NFIP is a federal program administered by FEMA that provides flood coverage to homeowners in participating communities. Policies are sold through licensed agents, with coverage limits set by the program.
Private flood insurance is offered by commercial carriers and can provide higher coverage limits, additional options, and replacement cost coverage on your home’s structure. The trade-off is risk-based pricing, so your premium may be higher or lower than NFIP depending on your property’s flood risk.
| Option | Best For | Key Considerations |
|---|---|---|
| NFIP Policy | Most homeowners in flood zones | 30-day waiting period, capped limits |
| Private Flood Policy | High-value homes, faster start dates | Risk-based pricing, varies by carrier |
Because flood insurance is complex and rules differ between federal and private programs, working with an independent agency helps. At Glenn Davis Insurance, we compare flood coverage options across multiple carriers to find the right fit for your property and budget.
Flood Zones, Elevation Certificates, and Your Premium
Your flood insurance premium is a calculation based on your property’s specific risk profile. Understanding the levers that drive it is key to saving money.
The Foundation: Flood Zones and the FIRM
Your premium starts with your property’s location on a FEMA Flood Insurance Rate Map (FIRM), which divides communities into zones reflecting flood likelihood. Homes in a Special Flood Hazard Area (SFHA), often Zone A or Zone V, face the highest risk and premiums. Properties in moderate- or low-risk zones may qualify for lower-cost Preferred Risk Policies.
The flood zone is only the starting point. Two identical homes in the same zone can have dramatically different premiums based on individual characteristics, the most important captured in an elevation certificate.
The Elevation Certificate: Your Premium’s Best Friend
An elevation certificate is a formal document, prepared by a licensed land surveyor or engineer, recording your home’s elevation relative to the Base Flood Elevation (BFE), the projected height floodwaters reach during a base flood.
The relationship is simple: the higher your home’s lowest floor is above the BFE, the lower your risk and premium. A home one foot above the BFE pays significantly less than one at or below it.
An elevation certificate typically costs between $300 and $800. In a high-risk zone, the premium difference between a home at the BFE and one two feet above it can be thousands of dollars per year, so the certificate often pays for itself in a single policy term.
If you are buying a home in [a flood](/billing-claims/) zone, always request a copy of the existing elevation certificate from the seller. If one does not exist, factor the cost of obtaining one into your purchase decision. It is a small investment that can save you a substantial amount over the life of your policy.
How Home Improvements Change Your Risk Profile
Your flood risk changes with every renovation. This is where you have direct control over your premium.
Actions that can lower your premium:
- Elevating your home: Raising your home’s lowest floor above the BFE is the single most effective mitigation measure. While costly, it can dramatically reduce your premium and may be eligible for FEMA’s Increased Cost of Compliance (ICC) coverage, which provides up to $30,000 to help with elevation costs after a flood.
- Installing flood vents: If you have an enclosed area below the BFE (like a crawlspace or a garage), installing engineered flood vents allows water to flow through, reducing hydrostatic pressure and structural damage. This can lower your premium.
- Elevating utilities: Moving your HVAC system, water heater, and electrical panel to a higher floor or to the attic can reduce potential damage and may qualify you for a lower rate.
Actions that can raise your premium:
- Finishing a basement: Adding living space below the BFE increases your exposure and will almost certainly raise your premium. This is a critical consideration before you undertake a basement renovation.
- Enclosing an area under your home: Without proper flood vents, enclosing a crawlspace or the area under a raised home can increase hydrostatic pressure and damage, leading to higher rates.
The 30-Day Waiting Period and Your Renovation Timeline
If you make a mitigation improvement that should lower your premium, you must provide documentation and request a policy change, which is subject to the same 30-day waiting period as a new policy.
The most financially savvy flood insurance policyholders treat their premium as an active, manageable cost. They obtain an elevation certificate, they make strategic home improvements that lower their risk, and they document every change with their insurer. This proactive approach can turn a mandatory expense into a manageable one, and it is the difference between simply having coverage and having coverage at the right price.
Your flood risk is not a fixed destiny; it is a variable you can influence. An elevation certificate is the first step.
The Claims Process: What to Expect After Flooding
Filing a flood claim is fundamentally different from a standard homeowners claim, and knowing the procedural differences can save you from costly mistakes.
Step 1: Immediate Notification and Documentation
The moment it is safe, contact your agent or carrier to file a claim. For NFIP policies, you will be assigned a claim number. Your first priority is documentation: before moving any item, take extensive photographs and video of water levels, damaged property, and structural issues. This evidence is your primary defense in a dispute.
Step 2: The Adjuster’s Role and Timeline
Unlike standard claims where an adjuster may be available within days, flood claims, especially after a declared disaster, can overwhelm the system. FEMA and private carriers often bring in adjusters from across the country, and in a major event you may wait several weeks for an initial inspection.
A crucial difference is the adjuster’s approach: they are not just assessing damage but verifying it was caused by the covered peril of flooding, not excluded causes like sewer backup or groundwater seepage.
Step 3: The Proof of Loss Requirement
This is a significant procedural hurdle unique to NFIP policies. Within 60 days of the loss, you must submit a formal, sworn Proof of Loss form, a detailed, itemized statement of damaged property and your claimed amount. It is a legal document, not a simple estimate. Missing the deadline can jeopardize your claim, so begin preparing it immediately after the adjuster’s visit.
Step 4: Settlement and Payment
Once the adjuster’s report and Proof of Loss are processed, the insurer issues payment. NFIP building coverage is typically paid on a Replacement Cost Value (RCV) basis if your home is your primary residence and you carry coverage of at least 80% of its replacement value. Personal property is almost always settled on an Actual Cash Value (ACV) basis, with depreciation subtracted.
A common and costly mistake is discarding damaged items before the adjuster has seen them. Flood policies require you to preserve damaged property for inspection. If you remove a ruined couch or tear out wet drywall before the adjuster arrives, you risk having that item excluded from your settlement. If you must remove items to prevent mold, photograph them extensively and keep them in a separate pile for the adjuster.
Another frequent error is failing to file a Proof of Loss for NFIP claims. This is a separate, sworn document that many homeowners do not realize they must submit. Your adjuster will provide the form, but you are responsible for completing and filing it within the deadline.
The Role of Mitigation in Your Claim
Your policy requires you to take reasonable steps to prevent further damage, such as covering a broken window with plywood or moving undamaged furniture to a dry area. These mitigation costs are often reimbursable, but you must keep every receipt.
The Appeals Process
If you disagree with the adjuster’s assessment, you have the right to appeal. For NFIP claims, you can submit a supplemental claim with additional documentation or request reconsideration. If that fails, you can hire a public adjuster or attorney specializing in flood claims.
The flood claims process is a marathon, not a sprint. The most successful claims come from homeowners who treat documentation as a full-time job in the first 48 hours, understand the Proof of Loss requirement, and are prepared to appeal an initial lowball offer. This level of preparation is what separates a smooth settlement from a months-long battle.
Understanding these procedural nuances is the difference between a successful recovery and a financial disaster.
Conclusion: Protecting Your Home From Rising Water
Flood damage is excluded from standard homeowners insurance, a gap you cannot afford to discover after the water recedes. Understanding the difference between water damage and flood damage, the 30-day waiting period, and the claims process puts you ahead of most homeowners.
The right time to buy flood insurance is before you need it. At Glenn Davis Insurance, our team has served Texas homeowners since 1974 and understands the flood risks specific to the region. As an independent agency, we compare flood coverage options across multiple carriers to find the right protection at the best price. Contact us for a complimentary quote and policy review.
Frequently Asked Questions
Do regular home insurance policies cover flood damage?
No. Standard homeowners insurance policies exclude flood damage. Flooding is defined as rising water or surface water from outside your home, such as heavy rain, storm surge, or overflowing rivers. If a flood damages your property, you will need a separate flood insurance policy to cover repairs and replacement. Your homeowners policy may cover other water damage, like a burst pipe, but not water entering from the ground or outside.
What type of water damage is not covered by insurance?
Water damage from flooding is not covered by a standard homeowners policy. This includes rising water, surface water, groundwater seepage, and storm surge. Gradual damage, such as a slow leak that develops over months, is also typically excluded because it is considered a maintenance issue. Sudden and accidental water damage from an internal source, like a burst pipe, is usually covered, but sewer backup and sump pump failure often require a separate endorsement.
How long is the flood insurance waiting period?
Most flood insurance policies have a 30-day waiting period before coverage takes effect. This means you cannot buy a policy and file a claim for a flood that happens the next day. The waiting period exists to prevent people from purchasing coverage only when a storm is forecast. A few exceptions apply, such as when you are buying a policy because a lender requires it for a new mortgage. Plan ahead and purchase flood insurance well before flood season begins.
Is flood insurance mandatory for all homeowners?
No, but it is required if your home is in a high-risk flood zone, known as a Special Flood Hazard Area, and you have a federally backed mortgage. Even if it is not required, flood insurance is strongly recommended. Any home can flood, and relying on federal disaster assistance is risky, as it often comes in the form of a loan you must repay, not a grant.
Get started with Glenn Davis Insurance and make sure your home is protected against rising water.